Financing
A house of your own,
from 200 to 1 600 € a month.
Rent it out instead and your guests cover the payment, and the house still becomes yours. How renting out works →
Work out your monthly cost →Your monthly cost
What would your dream house cost a month?
Pick your house, your country and your situation. We'll show you the cheapest route we know of, with a real rate published by a lender or central bank in that country.
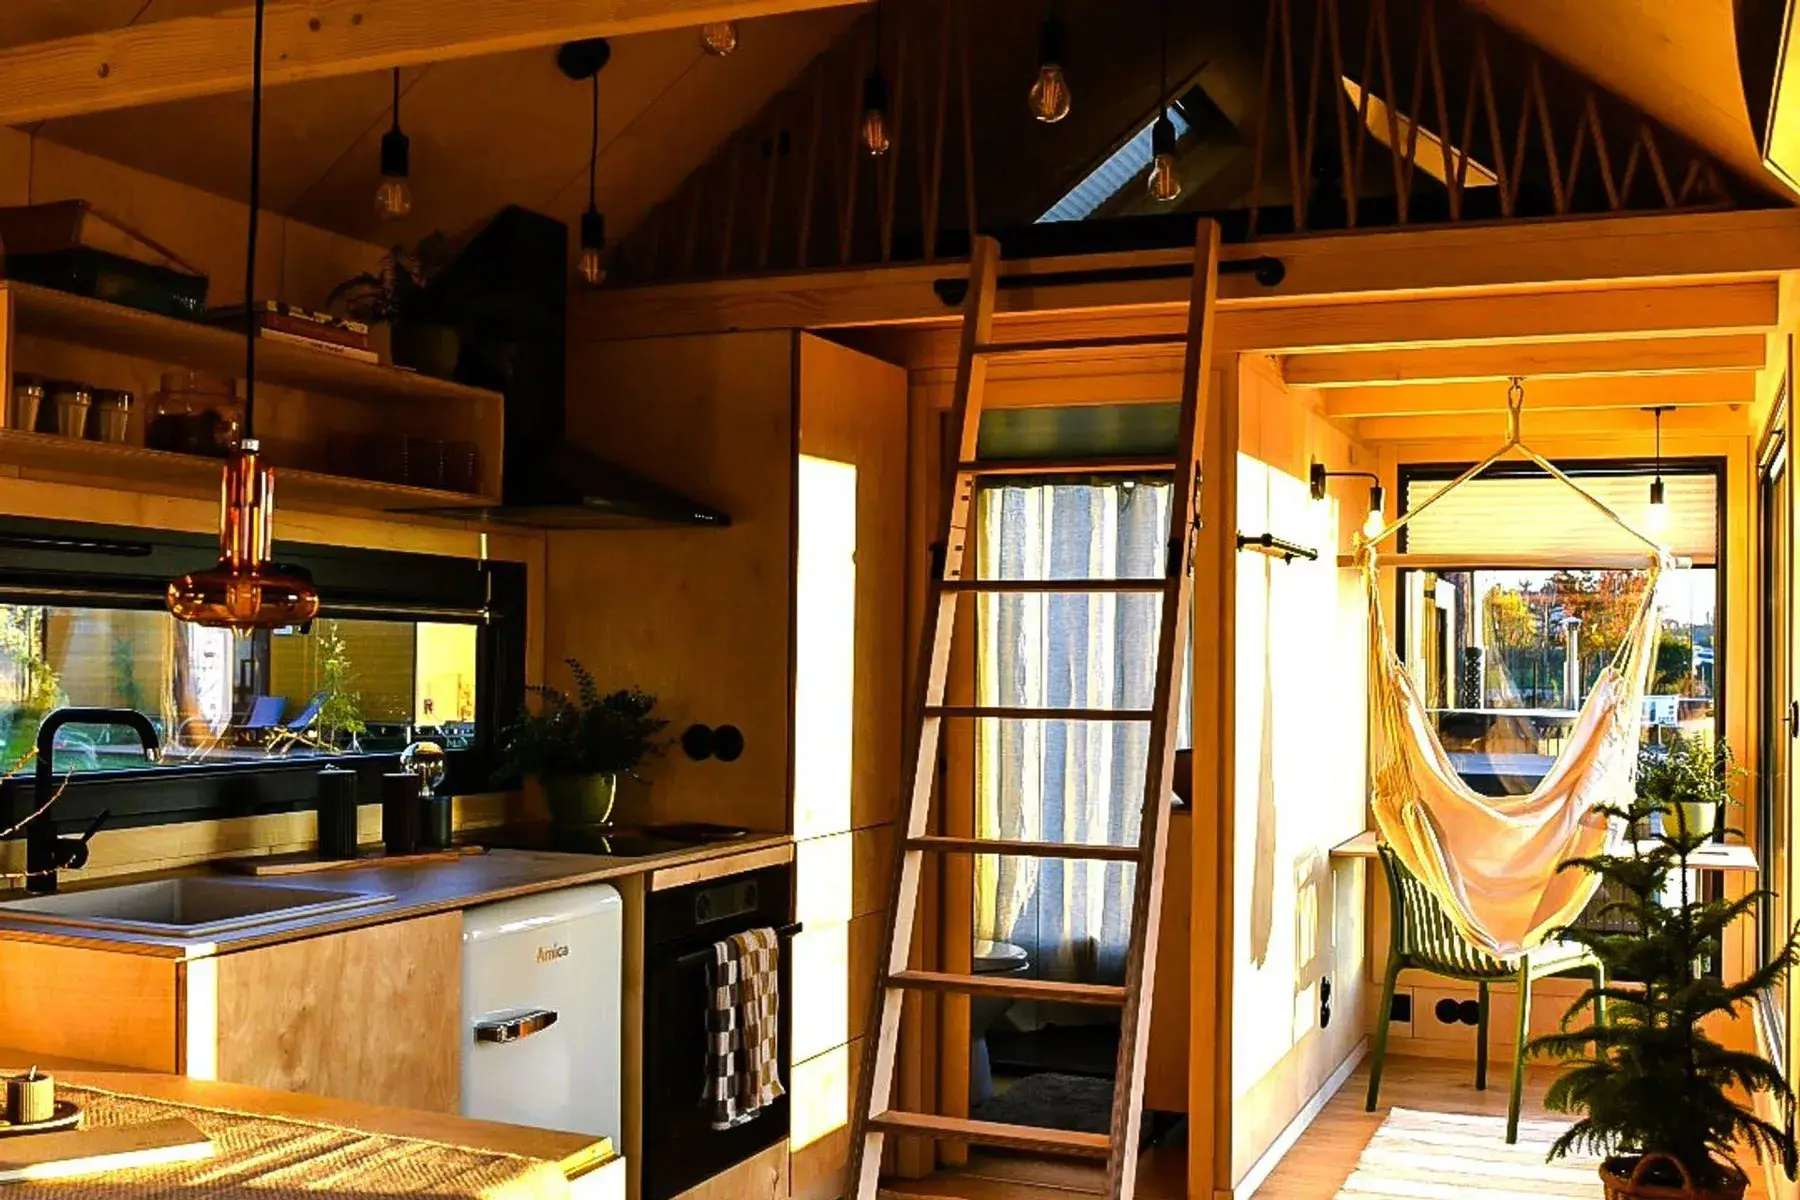
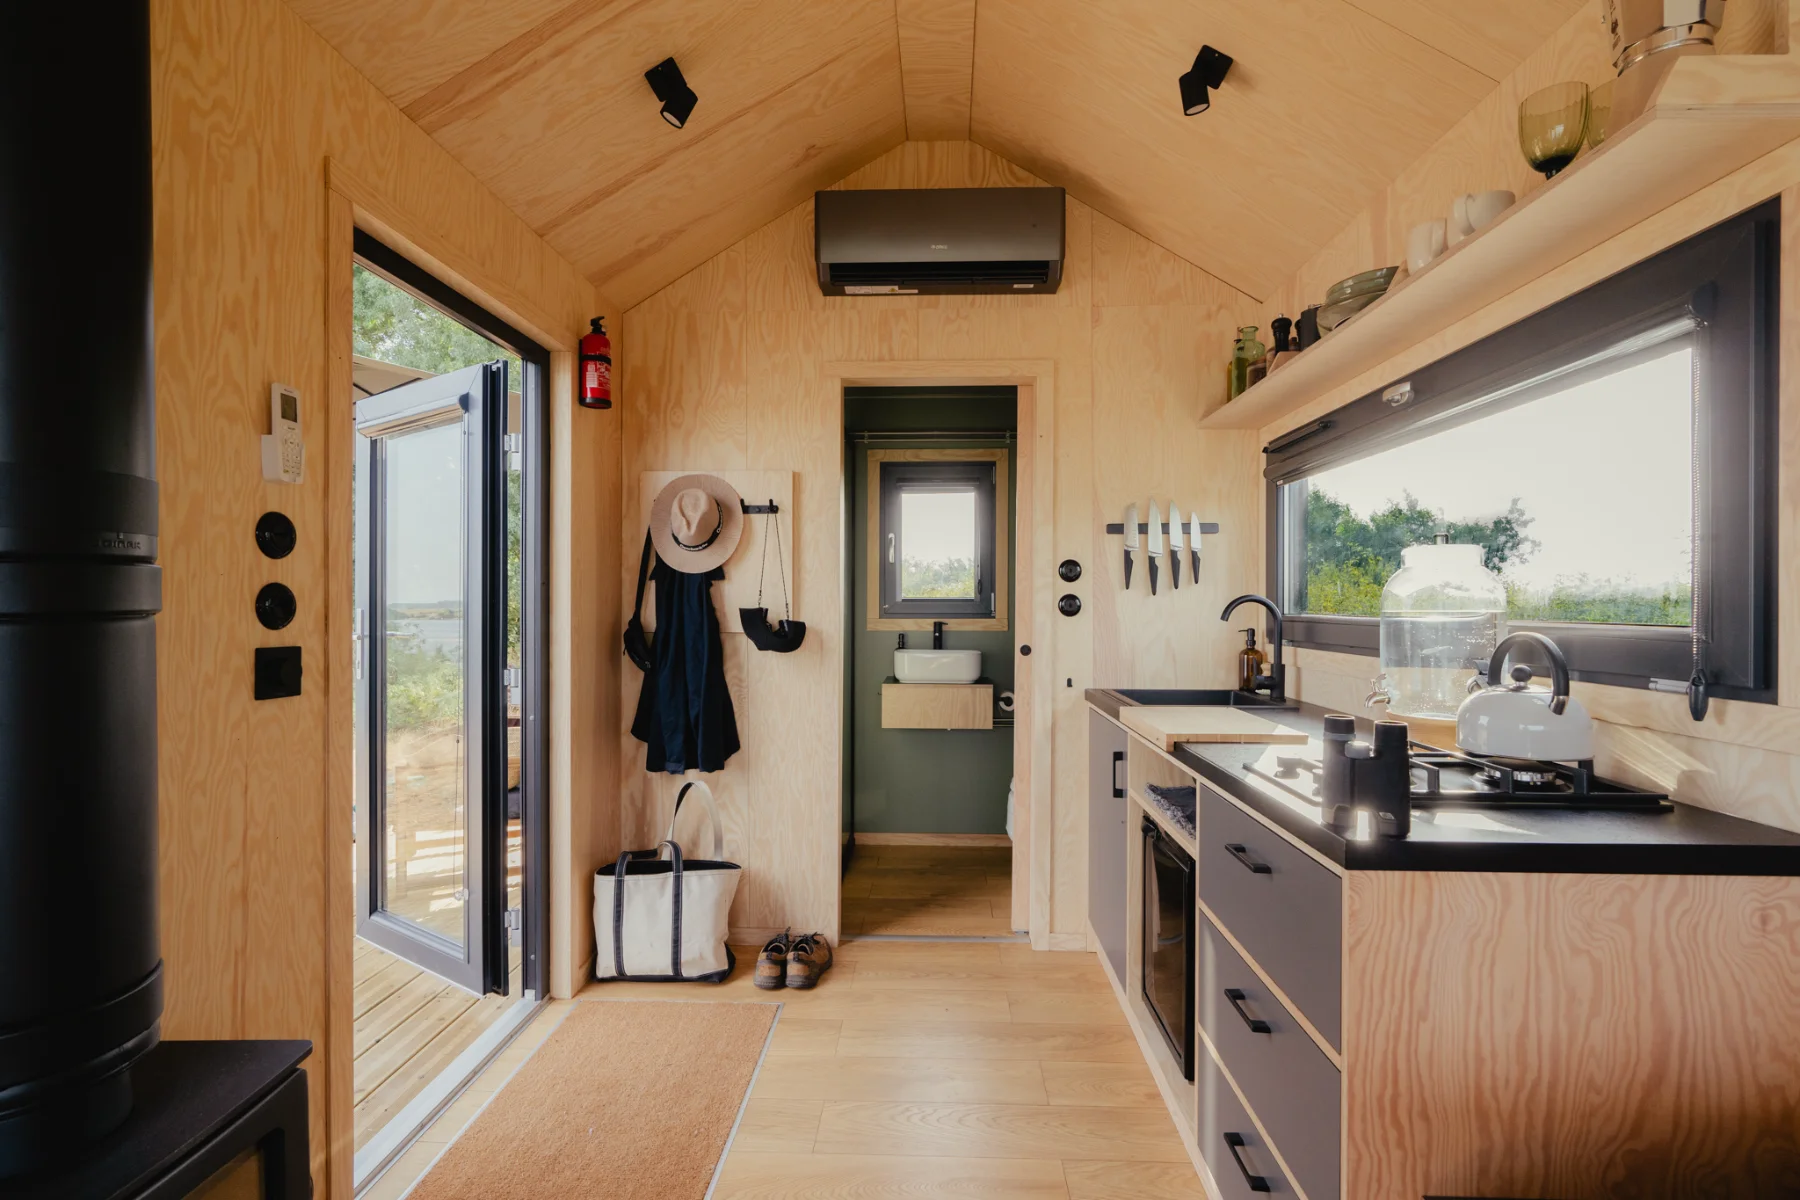
A kitchen, a bathroom with shower, toilet and water heater, electric heating, a bed and a table with seating. Ready to move into.
a month,
Rate, term and total
These figures are for the house. Land, groundwork, connections and permit fees come on top, and a lender will count them in. Borrowing money costs money. This is a worked example from a published rate, not an offer or a quote. Your own rate, term and fees depend on the lender, who makes the decision. Figures are in euro and exclude lender fees; your lender will quote in your own currency.
Where you can put it
This is the short version. The full rules for all fourteen countries are in our FAQ, with the law or the authority's own guidance cited, so you can take them to your building office. National rules as we last checked them. Municipalities add their own, and nothing here is legal advice.
Buying as a business? Then you can lease. The lessor owns the house, you pay monthly, and the payments are a business cost. Here's what a lease costs for your houses.
A kitchen, a bathroom with shower, toilet and water heater, electric heating, a bed and a table with seating. Ready to move into.
See what it earns in the Rent them out calculator →
Over 72 months, nothing to pay at the start or at the end, about 8.4%. Our leasing partner's indicative terms (September 2026), excluding VAT. Not an offer: every lease goes through the lessor's own credit check.
Routes
Six ways to pay for it
Which routes are open to you depends mostly on one thing: whether your house stays movable or becomes part of the land. A house on a foundation can carry a mortgage. A house that can be moved can be leased, financed like a vehicle and taken with you. We'll tell you which side of that line your model sits on before you order.
You own a home or the land
2.8–5.3%Borrow against your homeYour bank lends more on the home you already have.
Usually the cheapest money you'll ever be offered, because your bank already holds security it trusts. Published average home loan rates across our markets run from 2.8 to 5.3%. How much you can add is capped against the value of your home, and some banks want the project described as an improvement to your property.
- On wheelsYes
- Steel frameYes
- FoundationYes, cheapest
A mortgage on the new houseFor a modular home on land you own.
Only where the house becomes part of land you own, is permitted as a dwelling and can be entered in the land register. Longest terms, lowest rates, most paperwork: 2.8 to 5.3%, with 10 to 20% of your own money. If you're buying the land too, it starts as a building credit paid out in stages and becomes the mortgage once the house is signed off.
- On wheelsNo
- Steel frameSometimes
- FoundationYes
The house goes on rented land
3.8–11.6%A loan with no securityAgainst your income, up to 15 years.3.8–11.6%
A specialist lender lends against your income rather than property. Some take part of your salary or the house itself as cover instead. The specialists we work with lend 10 000 to 50 000 € with no security at all, or 50 000 to 125 000 € against the house with 20% of your own money and up to 15 years, and can pay out in our three instalments. Ask us who lends where you live.
- On wheelsBest fit
- Steel frameBest fit
- FoundationPossible, costs more
Leisure vehicle financeMobile houses registered as a caravan.5.5–9%
The same lending caravans and motorhomes use, secured on the registration document: 5.5 to 9% on lenders' own examples, terms up to 15 years, usually with about 20% down. Our mobile houses stand on a permanent galvanised trailer that can be registered as a caravan. Each lender sets its own rules on registration and weight, and in some markets we haven't found one who'll do it yet. In Norway, none of the four lenders we asked does it today.
- On wheelsIf registered
- Steel frameToo heavy
- FoundationNo
Finance part of the priceThrough our partner lender, up to about 31 000 € over 12 years.just under 7%
Credit arranged as part of the purchase, with no charge on the house, so the model doesn't matter. Where we have a lender in place: up to about 31 000 € over twelve years at just under 7%, with 20% paid to us as a deposit. Elsewhere the usual ceiling is about 10 000 € over 36 months, enough for options rather than a house. An approved credit is valid for three months and a custom build takes three to six, so it's best to apply part way through the build.
- On wheelsUp to 31 000 €
- Steel frameUp to 31 000 €
- FoundationUp to 31 000 €
You buy as a business
about 8.4%Business lease72 months, no down payment, nothing to pay at the end.
The lessor owns the house and you pay monthly. Business customers only, and the house has to stay movable: about 1 775 € a month for every 100 000 € of house over 72 months, about 8.4%. These are our leasing partner's indicative terms from September 2026, not an offer.
- On wheelsYes
- Steel frameBest fit
- FoundationIf demountable
We arrange financing ourselves in Sweden, Germany and Norway, where we work directly with the lenders. Elsewhere we know the shape of the market rather than every lender in it, so tell us where your house will stand and we'll find out what's open to you before you count on it.
Next steps
From here to keys, in five steps
- Step 1Design your house
- Step 2We send what your lender needs
- Step 3You apply to the lender
- Step 4We start the build
- Step 5Delivery
“Great price, quality and communication throughout the process.The delivery went fast and smooth, and I am very satisfied overall.”
“It’s been two and a half years since I bought a tiny house from Vagabond Haven. I haven’t regretted my decision for a single moment and am still incredibly happy with my light-filled Sunshine house. It offers plenty of storage in a compact space, the materials are high quality and the craftsmanship is superb.”
“Ordering the cabin was smooth. I bought a ready-built house, which exceeded my expectations in many ways when it arrived. My cabin was delivered as agreed to a challenging site without any problems. The driver set the house in place and showed me the equipment.”
“Excellent advice, friendly contact, trouble-free delivery, good quality, and a reduced price thanks to a special offer. Thanks to the Vagabond Haven team. Keep it up!”
Questions
What our customers usually ask
What happens once I've decided to buy?
- Design your house. Put your house together in the configurator, then ask us for the documents. We need the model, roughly where it'll stand, and whether you own the ground.
- We send what your lender needs. A written quote, the specification, the weight and dimensions, the permit position for your municipality and the document list your lender works from. If you're borrowing from your own bank, we also send a pack written for your adviser. One email, nothing for you to chase.
- You apply to the lender. You borrow from the lender, not from us, so the credit agreement is between you and them. Nobody pays us to steer you towards one lender.
- We start the build. Three to six months for a custom build (four to eight weeks for the Nature Pod), two to four weeks for a house in stock. Payments usually run 30% when you sign, 50% during the build and 20% before delivery, or half and half for a house in stock. We can adjust that if you need us to, and whatever we agree goes into your contract.
- Delivery. We deliver to your plot, connect the house and do the final check on site. The five-year warranty starts there (two years on the Nature Pod).
Do you lend the money yourselves?
No. You borrow from a bank or leasing company that is licensed to lend. That gives you the consumer protection of a regulated credit agreement, and a rate from someone who borrows money far more cheaply than we could.
Can I get a mortgage on it?
Yes, in two ways. The cheapest is usually to increase the mortgage on a home you already own and pay for the house with that. This works for every model. A mortgage on the house itself is possible for a modular home on a permanent foundation, on land you own and with a permanent building permit, because it then becomes part of the property. Banks treat it like any small house, though some, for example in Germany, ask for a minimum living area. A mobile or semi-mobile house stays movable property, so banks don't take it as security for a mortgage. For those, a consumer loan or, for businesses, leasing is the usual route. Ask your bank, and we'll send the documents it needs.
I already have a mortgage. Is borrowing more on it really cheaper?
Usually, and by a wide margin, because the bank already holds security it trusts. The catch: the amount you can add is capped against your home's value, that cap has been tightened in some countries, and some banks want the project described as an improvement to your property. Ask your own bank first, then get one comparison offer.
Can I lease one as a private person?
In most countries we sell in, no. Leasing for this kind of house is offered to businesses, because a private lease with a purchase option counts as consumer credit and few lessors set that up. If you buy through a company, it's often the best route.
Does it help if the house is road-registered?
It opens a route that's otherwise closed, though not necessarily the best one. Registered as a trailer, the house can use caravan and motorhome finance (up to fifteen years in some countries, with the house as security) and one insurance policy for the whole EU. If you already own property, borrowing more on that is still cheaper. Only our mobile range can be registered, because it has to fit the legal limits for a trailer.
What do you get out of arranging this?
Houses sell when people can afford them, and that's our whole interest. No lender pays us anything today. If that ever changes, we'll say so on this page, next to the route it applies to, and it won't change what we recommend.
The monthly figure looks too good. What's missing?
Look at the total you repay, not just the month. A longer term always makes the month smaller and the total larger. A bigger house over fifteen years can cost less per month than a smaller one over seven, and far more in the end. That's why both numbers sit next to each other in the calculator.
Talk to us
Want to find out if you can have your dream home for 200 to 1 600 € a month?
Write to us and we'll tell you which routes are open where you are, what they cost and what a lender will want to see. No obligation, and no credit application until you decide to make one.
Thank you. Your message is on its way to us, and we'll be in touch.
We use this to answer you and to work out which routes apply where your house will stand. We don't ask what you earn, this isn't a credit application, and we don't pass your details to a lender unless you ask us to. How we handle your data.
How the figures on this page are worked out
The monthly range is the lowest and the highest figure the calculator gives for a house someone can live in, across every model, every country we deliver to and both the furnished and the off-grid specification. The low end is a fully furnished Nature Pod at 32 500 € over twenty-five years at 3.6%, with the 25% deposit the cheapest lenders in our markets ask for: 123 € a month. An empty house would be cheaper still, from 66 €, but it isn't a house to live in, so we don't quote it. The high end is a fully off-grid Evergreen at 94 000 € on a loan with no security, 8.85% over five years: 1 551 € a month, covering 75 000 € of the price, because that's the ceiling for the route. Both ends are rounded up to the nearest hundred, not down.
Prices exclude VAT and are base prices before options. Nothing on this page is an offer of credit, a credit quotation or financial advice.